Can You Still Get Homeowners Insurance in Orange County in 2026?
California’s insurance market is changing quickly. Here is what Orange County buyers, sellers, and homeowners need to know before insurance becomes a last-minute problem.
For many Orange County homeowners, insurance used to be something handled quietly near the end of a real estate transaction.
That has changed.
Today, insurance availability, wildfire exposure, premiums, property condition, and carrier requirements can influence whether a buyer feels comfortable purchasing a home—or whether financing can move forward at all.
And this is no longer a concern limited to homes deep in the mountains.
Orange County had more than 26,000 residential California FAIR Plan policies by June 2026, compared with roughly 4,000 in September 2021, according to recently compiled FAIR Plan data.
That increase tells us something important:
Homeowners insurance needs to be part of the real estate strategy earlier than it used to be.
Key Takeaways
- Homeowners insurance is still available in Orange County, but certain properties may have fewer carrier options.
- Homes in higher wildfire-risk areas can be more difficult or expensive to insure.
- The California FAIR Plan is designed as an insurer of last resort, not necessarily a first-choice replacement for traditional coverage.
- Buyers should investigate insurance before removing important contingencies.
- Sellers may benefit from understanding their property’s insurance situation before listing.
- A low purchase price does not automatically mean a property will be inexpensive to own.
- Insurance should be evaluated alongside mortgage payment, taxes, HOA dues, repairs, and other ownership costs.
Why Has Home Insurance Become More Difficult in California?
California insurers have been dealing with a combination of:
- Wildfire losses
- Rising construction costs
- Reinsurance costs
- Climate-related risk modeling
- Increasing claim severity
- Regulatory constraints
- Concentrated exposure in higher-risk areas
Some carriers have reduced new business or changed where and how they write policies.
The California Department of Insurance has been implementing reforms intended to stabilize the market and encourage more private insurers to write coverage, while also revising the state’s rate-review process.
For homeowners, however, those changes do not necessarily produce immediate relief.
Insurance remains highly property-specific.
What Is the California FAIR Plan?
The California FAIR Plan provides basic property insurance when homeowners cannot obtain coverage through the traditional insurance market.
It is often described as California’s insurer of last resort.
That distinction matters.
FAIR Plan coverage may not provide all of the protection included in a standard homeowners policy.
Homeowners may need additional coverage—commonly called a Difference in Conditions policy—for risks or liability protection not included under the FAIR Plan.
The right structure should be reviewed with a licensed insurance professional.
Why Are More Orange County Homes Using the FAIR Plan?
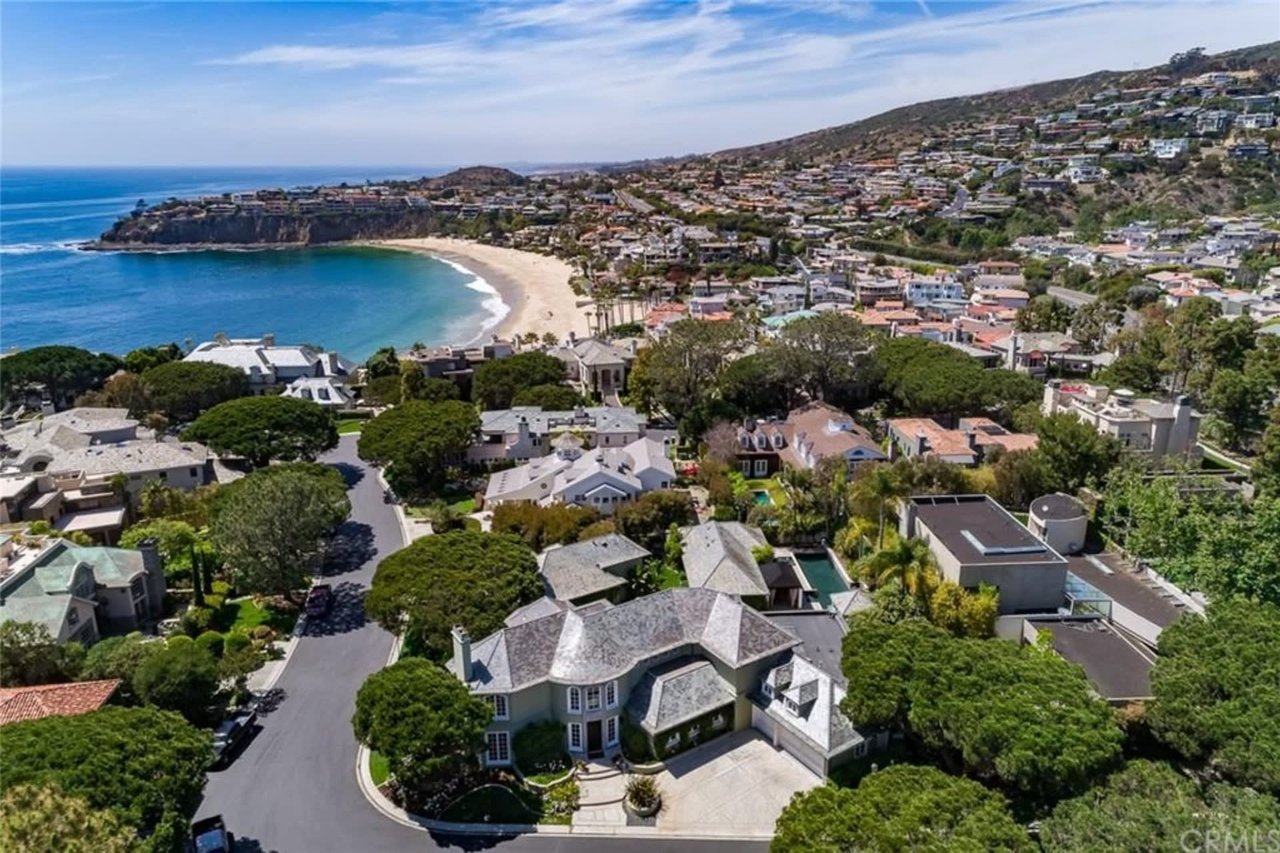
Orange County includes many communities near:
- Hillsides
- Open space
- Canyons
- Wildland-urban interface areas
As carriers reassess wildfire risk, some properties that previously had multiple insurance options may have fewer.
Recent FAIR Plan figures show Orange County residential policies increasing from approximately 4,015 in September 2021 to 26,812 by June 2026.
That does not mean 26,000 homes are uninsurable.
It means a significantly larger number of homeowners are relying on California’s residual insurance market.
Which Orange County Properties May Face Greater Insurance Challenges?
Insurance decisions are made property by property, but additional scrutiny may occur for homes with characteristics such as:
- Higher wildfire exposure
- Hillside or canyon locations
- Dense vegetation
- Older roofs
- Certain roof materials
- Deferred maintenance
- Older electrical systems
- Limited defensible space
- Prior claims
Location matters.
Condition matters.
Carrier guidelines matter.
That is why two homes in the same city can receive very different insurance quotes.
Buyers: Do Not Wait Until the End of Escrow
This may be the most important takeaway for buyers.
Get an insurance quote early.
Do not assume:
“The current owner has insurance, so I will too.”
A seller’s existing policy may not transfer.
The carrier may not be writing new policies.
The premium may change.
Coverage requirements may differ.
Before removing contingencies, understand:
- Whether insurance is available
- Which carrier will write the policy
- Estimated annual premium
- Deductible
- Wildfire coverage
- Exclusions
- FAIR Plan requirements
- Whether additional coverage is needed
This becomes especially important if your lender requires specific insurance limits.
Insurance Can Affect Your Monthly Housing Cost
Buyers often focus on:
- Mortgage payment
- Property taxes
- HOA dues
Insurance deserves equal attention.
A property may fit comfortably at one premium but become less attractive if insurance costs are substantially higher than expected.
This is particularly important in today’s market because buyers are already dealing with elevated mortgage rates.
When affordability is stretched, every recurring ownership cost matters.
Sellers: Understand the Insurance Question Before Buyers Ask
Insurance can also affect sellers.
Imagine placing your home on the market, receiving an offer, going into escrow—and then discovering the buyer cannot find acceptable insurance at the cost they expected.
That can create:
- Delays
- Renegotiation
- Buyer hesitation
- Cancellation risk
Before listing a property in a potentially challenging insurance area, consider discussing the situation with a knowledgeable insurance professional.
You may want to understand:
- Current policy
- Carrier
- Premium
- Recent insurance history
- Known risk factors
- Available alternatives
You are not responsible for obtaining coverage for the buyer.
But understanding the issue can help prevent surprises.
Does a FAIR Plan Policy Make a Home Harder to Sell?
Not automatically.
Many homes sell with FAIR Plan coverage.
The bigger issue is whether the buyer understands:
- Availability
- Cost
- Coverage limitations
- Additional policy needs
Transparency helps.
If insurance is likely to be a concern, dealing with it early is much easier than allowing it to become a surprise near closing.
Can Buyers Negotiate Because Insurance Is Expensive?
Potentially.
Insurance cost can become part of the overall affordability conversation.
A buyer may decide to negotiate:
- Purchase price
- Seller credit
- Repair
- Vegetation management
- Roof work
Whether the seller agrees depends on:
- Market conditions
- Competition
- Property condition
- Seller motivation
Insurance does not automatically create a seller obligation.
It can, however, affect what a buyer is willing to pay.
Property Condition May Matter More Than Sellers Realize
Some insurance concerns are tied to the home itself rather than only its location.
Before listing, sellers may benefit from evaluating:
- Roof condition
- Electrical panels
- Exterior maintenance
- Vegetation
- Tree clearance
- Debris
- Gutters
- Visible hazards
This connects directly to a broader pre-listing strategy.
Before spending money indiscriminately, see our guide on what not to do before selling your Orange County home.
The goal is to identify which improvements actually reduce friction for buyers.
What About Wildfire Mitigation?
Home-hardening and defensible-space improvements can help reduce wildfire exposure.
Examples may include:
- Clearing combustible vegetation near structures
- Maintaining roofs and gutters
- Managing trees and shrubs
- Using ember-resistant materials
- Reducing combustible items near the home
Specific mitigation standards vary, and homeowners should rely on qualified fire-safety and insurance guidance.
The objective is not simply obtaining insurance.
It is reducing actual risk.
Is California Trying to Fix the Insurance Market?
Yes.
California’s Department of Insurance has been implementing its Sustainable Insurance Strategy, designed to encourage carriers to return to higher-risk areas while modernizing rate review and allowing more sophisticated catastrophe modeling.
The Department continues issuing regulatory updates, including an October 19 announcement expanding transparency around the insurance-rate review process.
That is encouraging.
But homeowners should not assume market changes will immediately solve an individual property’s insurance challenge.
Should You Avoid Buying a Home Because It Needs the FAIR Plan?
Not necessarily.
But understand what you are buying.
Evaluate:
- Insurance premium
- Supplemental coverage
- Deductibles
- Fire risk
- Property condition
- Long-term ownership cost
- Resale implications
Then decide whether the overall property still fits your goals.
A home should not be judged on one cost alone.
But no major ownership cost should be ignored either.
What Should Current Homeowners Do?
Even if you are not moving, review your coverage.
Confirm:
- Dwelling limit
- Replacement-cost assumptions
- Deductibles
- Additional living-expense coverage
- Personal-property coverage
- Liability protection
Construction costs can change.
Your policy may not automatically reflect the current cost to rebuild.
The California Department of Insurance has urged homeowners to review coverage before major disasters rather than discovering gaps afterward.
Five Questions to Ask Your Insurance Professional
Before buying or selling, ask:
- Can this property obtain standard homeowners coverage?
- What is the estimated annual premium?
- Would the FAIR Plan be required?
- Would I need supplemental coverage?
- Are there improvements that could expand carrier options or reduce risk?
Those five questions can uncover important information early.
Frequently Asked Questions
Can you still get homeowners insurance in Orange County?
Yes. Many homes continue to qualify for standard policies, while others may need alternative carriers or the California FAIR Plan. Availability depends on the property and insurer.
What is the California FAIR Plan?
It is California’s insurer-of-last-resort program providing basic property insurance when coverage cannot be obtained through the traditional market.
Is Orange County considered a wildfire-risk area?
Certain Orange County communities contain higher wildfire-risk zones, particularly near hillsides, canyons, and open space. Risk varies substantially by individual property.
Will homeowners insurance affect my mortgage approval?
Lenders generally require acceptable property insurance before closing. Buyers should verify lender requirements early.
Does the seller’s policy transfer to the buyer?
Generally, buyers obtain their own homeowners policy. Never assume the seller’s coverage or premium will continue after ownership changes.
Insurance Is Now Part of the Real Estate Conversation
A few years ago, insurance might have been a box checked near the end of escrow.
Today, that can be risky.
Buyers should understand insurance early.
Sellers should anticipate the question.
Homeowners should review their existing protection.
Because the true cost of owning a home is not simply:
Purchase price + mortgage.
It is the complete financial picture.
Buying or Selling an Orange County Home?
The Lynch Group helps clients evaluate more than the headline price.
We look at financing, insurance considerations, HOA costs, property condition, negotiation, and the factors that can affect whether a property makes sense long term.
Build My Orange County Strategy
About Cheryl Lynch
Cheryl Lynch is the Founder and CEO of The Lynch Group OC at Compass. With more than 26 years of Southern California real estate experience, Cheryl helps Orange County buyers and sellers understand the strategy, risks, costs, and opportunities behind major real estate decisions.
California DRE #01314572
Disclaimer: Insurance availability, premiums, underwriting guidelines, and coverage vary by property and carrier. This article provides general real estate information and is not insurance, legal, tax, or financial advice. Consult a licensed insurance professional regarding specific coverage.