Is a 2-1 Mortgage Rate Buydown Worth It in Orange County?
With mortgage rates remaining elevated, buyers are paying closer attention to something that received far less attention when rates were lower:
How the transaction is financed.
Freddie Mac reported the average 30-year fixed rate at 6.76% on September 10, 2026, up from 6.71% the week before. Freddie Mac
At Orange County purchase prices, even a fraction of a percentage point can materially affect a monthly payment.
One strategy buyers may encounter is a 2-1 temporary mortgage buydown.
It can be useful.
But it is not free money, and it is not right for every buyer.
What Is a 2-1 Buydown?
With a 2-1 buydown, funds are set aside at closing to temporarily reduce the buyer's effective mortgage payment.
Conceptually:
- Year 1: payment calculated at 2 percentage points below the note rate
- Year 2: payment calculated at 1 percentage point below
- Year 3 onward: full note-rate payment
For example, if the note rate were 6.75%:
- Year 1 payment would be based on approximately 4.75%
- Year 2 on approximately 5.75%
- Year 3 onward on 6.75%
The actual loan documents and qualification requirements are determined by the lender.
Who Pays for It?
Often, the cost is funded through a negotiated seller concession.
That can make a buydown particularly relevant when a home has:
- Been on the market longer
- Had a prior price reduction
- Limited competition
- A seller motivated to close
Instead of reducing the purchase price, a seller may agree to contribute money toward eligible financing costs.
Why Buyers Like Temporary Buydowns
The first years of ownership can be expensive.
Buyers may simultaneously face:
- Moving expenses
- New furniture
- Repairs
- Landscaping
- Childcare changes
- Renovations
- Higher utility costs
A temporary reduction in mortgage payments can create breathing room.
The Important Catch
The payment eventually increases.
A buyer should be comfortable with the full note-rate payment.
Do not buy a home that only works financially during the temporary buydown period.
Buydown or Price Reduction?
This is where the math becomes interesting.
Suppose a seller is willing to concede $20,000.
You could potentially use that value toward:
Option A: A lower purchase price.
Option B: Eligible closing costs or a rate-buoydown structure.
A price reduction lowers the loan balance.
A financing concession may have a larger short-term effect on monthly cash flow.
Neither is automatically superior.
Ask your lender to model both.
What Should You Compare?
Request side-by-side calculations showing:
- Purchase price
- Loan amount
- Note rate
- First-year payment
- Second-year payment
- Full payment
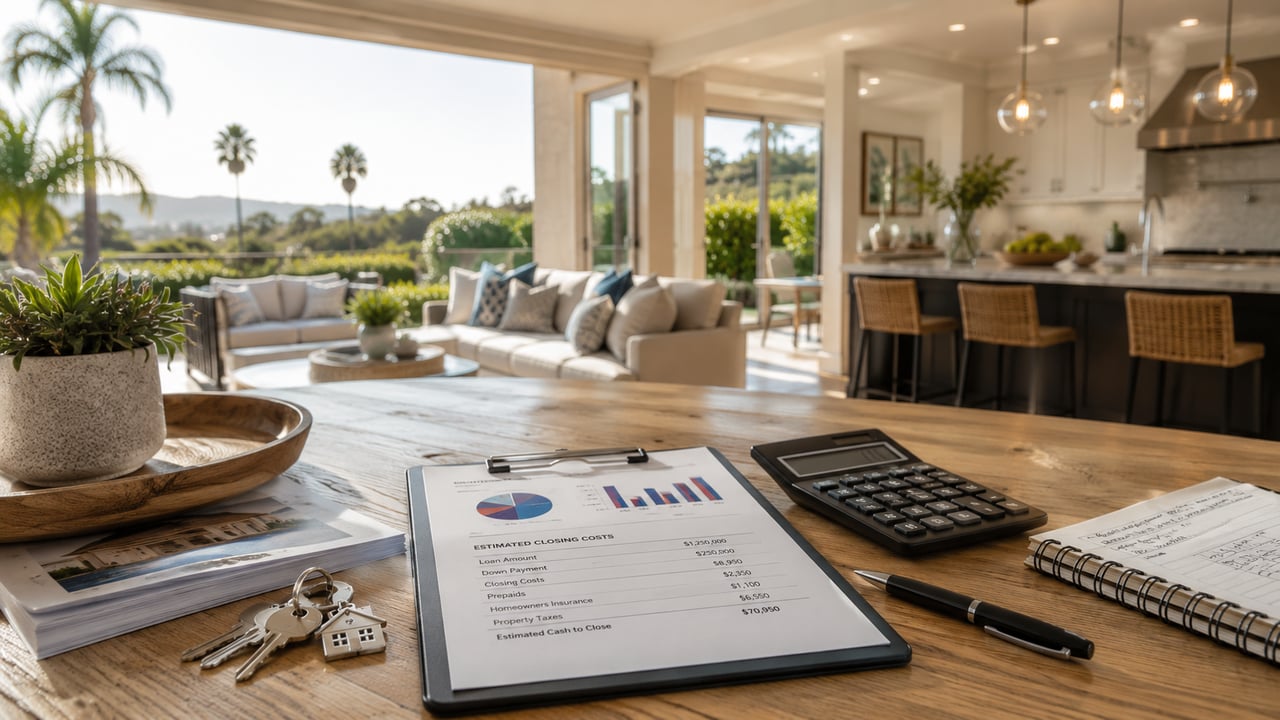
- Cash needed to close
- Cost of the buydown
- Break-even implications
Then choose based on your actual goals.
When a 2-1 Buydown May Make Sense
It may be attractive when:
- You expect income to increase
- You want additional liquidity after closing
- The seller is willing to fund it
- You are comfortable with the eventual full payment
- The lender approves the structure
When It May Not Make Sense
Think carefully when:
- The home's price itself appears unsupported
- You are stretching to qualify
- You are paying the buydown cost yourself and may move soon
- A permanent rate reduction offers better economics
- You are relying on a future refinance to make the home affordable
Could You Refinance Later?
Possibly.
But never build the purchase strategy around the assumption that refinancing will definitely be available.
Future rates, property value, credit, income, and lending rules can all change.
Frequently Asked Questions
Does a 2-1 buydown change my actual mortgage rate?
The note rate generally remains the same. Funds subsidize the payment during the temporary buydown period.
Does the buyer still have to qualify at the full rate?
Qualification depends on the mortgage product and lender requirements. Confirm with the lender before writing the offer.
Can every seller pay for a buydown?
Seller-concession rules vary by loan program and transaction structure.
Is a buydown better than negotiating the price?
Sometimes. The correct answer requires comparing the actual financial benefit of both options.
The Best Negotiation Is the One That Solves the Right Problem
If the problem is purchase price, negotiate value.
If the problem is upfront cash, examine closing costs.
If the problem is monthly affordability, examine financing options.